Mortgage Renewal on Salt Spring Island: What to Do Before You Sign
If your mortgage term ends in the next six months, a renewal letter from your lender is on its way. For a lot of Salt Spring Island homeowners, the easy move is to sign it and send it back. But renewal is one of the few times you can change lenders, terms or your whole mortgage strategy without paying a penalty. Here’s how to make the most of it.
The short version
- Start looking at your options 4 to 6 months before your term ends.
- Your renewal letter is an offer, not your only option.
- Switching lenders at renewal is often simpler than people expect.
- Island properties can affect which lenders are a good fit, so plan ahead.
When your renewal letter arrives
If your mortgage is with a federally regulated lender, like one of the big banks or large credit unions, they must send you a renewal statement at least 21 days before your term ends. That’s according to the Financial Consumer Agency of Canada. Local credit unions and other provincially regulated lenders can follow different timelines.
Here’s the catch: if you don’t respond, your mortgage may renew automatically on whatever terms your lender offered. Three weeks isn’t much time to compare options that are deemed appropriate to your circumstances and financial needs, gather documents and make a decision you’ll live with for the next several years.
That’s why I suggest starting the conversation 4 to 6 months before your renewal date. It gives you time to see what’s out there, and some lenders will let you secure an offer well before your term ends.
Renewing with your lender vs. switching lenders
Staying with your current lender is convenient. There’s no new application, no appraisal and usually no paperwork beyond a signature. Sometimes it’s the right choice. But convenience isn’t the same as the best fit.
Switching lenders at renewal means a new application. The new lender will review your income, credit and property, and there can be costs such as an appraisal, legal or discharge fees. Some lenders will cover some or all of those costs, so it’s worth asking.
Good news about the stress test
Borrowers who do a straight switch at renewal are not required to qualify at the higher stress test rate, as long as the switch is between federally regulated financial institutions and the mortgage amount and amortization stay the same. That makes it easier to move your mortgage if another lender is a better fit.
One important note: removing the prescribed stress test does not eliminate income verification, debt servicing assessment or other underwriting requirements.
If you want to borrow additional funds, structuring a separate home equity line of credit could allow you to keep your switch qualifications. However, if you’re refinancing or extending your amortization at renewal, standard mortgage qualification and stress test requirements generally apply. This is where having a well-thought-out financing strategy becomes especially important.
Why renewal can look different on Salt Spring Island
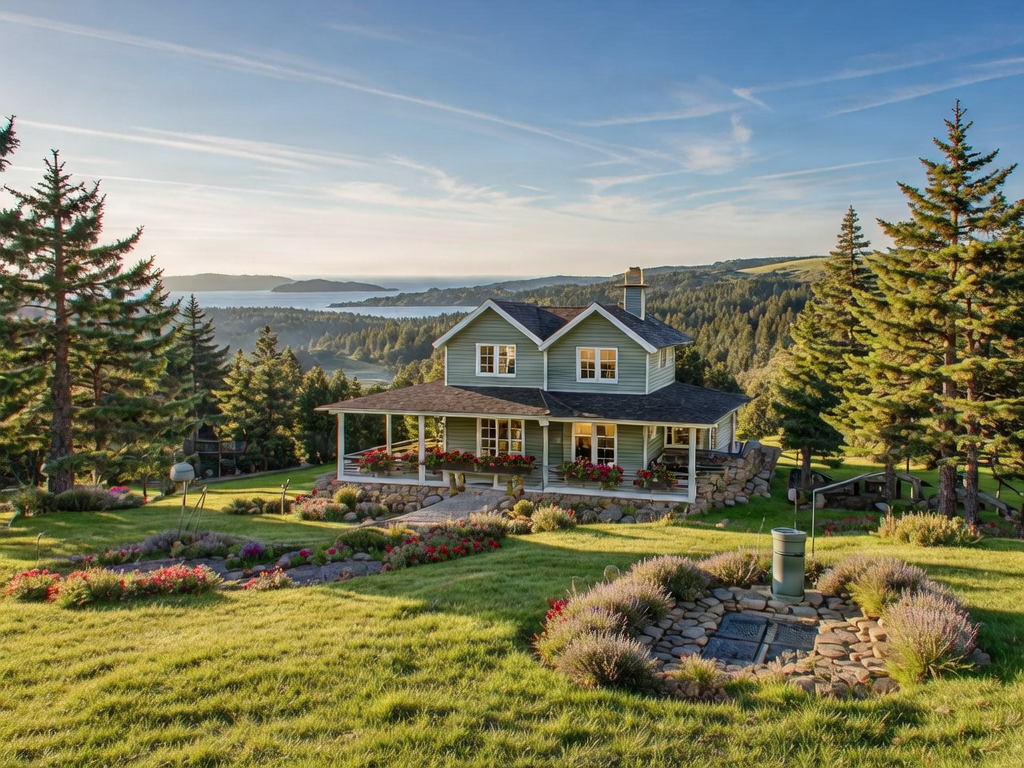
Your current lender already knows your home. A new lender sees it for the first time, and island properties don’t always fit the standard lending box. Rural acreage, waterfront homes, private wells and septic systems, older or owner-built homes and seasonal access can all affect how a lender views your property.
That doesn’t mean you can’t switch. It means it pays to know early which lenders are comfortable with Salt Spring homes like yours. I cover more of what island buyers and sellers should know in Buying or Selling on Salt Spring Island This Fall.
5 questions to ask before you renew
- Is my lender’s renewal offer actually competitive? The first offer isn’t always the best one. Compare it against what other lenders would offer you today.
- Does my term still fit my plans? If you might sell, move or downsize in the next few years, a shorter term or a portable mortgage could save you a penalty later.
- Could I save by switching lenders? Look at the full picture: rate, prepayment options, penalties and any switching costs.
- Fixed, variable or adjustable: which suits me now? Your comfort with payment changes may be different today than it was five years ago.
- What prepayment options do I need? If you expect a bonus, inheritance or sale of another property, flexible prepayment terms matter.
Renewal is a chance to rethink your mortgage
A lot can change in five years. Renewal is a natural time to ask whether your mortgage still fits your life, not just your budget. You might want to:
- Use your home equity for a renovation or to consolidate higher-interest debt
- Add or remove a borrower
- Adjust your payments as you plan for retirement
- Line up financing for a move on or off the island
These changes usually mean a refinance rather than a simple renewal, so the details matter. My Mortgage Strategy and Life Transitions pages explain how I help with each. If your income has changed since you last qualified, my guide to self-employed mortgages in BC may help too. And if your current lender has already said no to a change, read When Your Lender Said No.
Your Salt Spring Island mortgage renewal checklist
- Find your renewal (maturity) date on your annual mortgage statement
- Note your balance, current rate, payment and remaining amortization
- Gather recent income documents (pay stubs and T4s, or two years of financials if you’re self-employed)
- Have your latest property tax notice and home insurance details handy
- Think about your plans for the next five years
- Run a few numbers with my mortgage calculators
- Book a call 4 to 6 months before your renewal date
Frequently asked questions
Does it cost anything to use a mortgage broker at renewal?
For most standard residential mortgages, the lender pays the broker, so there’s no cost to you. If a fee ever applies to your situation, I’ll tell you upfront, before anything is signed.
Can I switch if my mortgage is with a credit union?
Usually, yes. At the end of your term you can generally move to another lender. Renewal timelines and terms vary between credit unions, so it’s worth checking your agreement early.
Can I renew early?
Some lenders let you renew a few months before your term ends without a penalty. Breaking your mortgage earlier than that can mean a prepayment penalty, so ask before you sign anything.
What if my renewal date has already passed?
Your mortgage may have renewed automatically. You may still have options, depending on the term you were renewed into. Get in touch and we’ll look at it together.
Talk to a Salt Spring Island mortgage broker
I spent more than 30 years inside Canadian banks and credit unions, and I’ve called Salt Spring home since 2016. Now I work for you, not the lender. If your renewal is coming up, let’s look at your options together, in plain language and with no pressure.
Start a conversation or call me at (250) 538-7133.
This article is for general information only and isn’t financial advice. Mortgage rules, lender policies and qualification criteria change, and every situation is different. Talk to a licensed mortgage professional about your own circumstances.